TL;DR
- The 2026 interim EMP501 covers 1 March 2026 to 31 August 2026. SARS opened submissions on 21 September and they close on 31 October 2026.
- 31 October is a Saturday this year, so aim to be done by Friday 30 October.
- Your EMP501 must agree three things: PAYE, UIF and SDL declared on your EMP201s, the payments you actually made, and the IRP5/IT3(a) certificates for each employee.
- Late submission costs 1% of annual PAYE, rising 1% a month to 10%. Unused ETI can be forfeited.
- Income tax numbers are mandatory. Missing ones can get your submission rejected.
What the interim EMP501 is for
Every month you tell SARS what you owe on the EMP201. Twice a year you prove it. The EMP501 reconciliation takes six months of declarations, six months of payments and the tax certificate for every employee, and checks that they agree.
SARS's 2026 interim notice, dated 31 August 2026, says your EMP501 must reflect:
- Reconciled PAYE, UIF and SDL values that match the EMP201s you submitted. Where these differ from the interim IRP5/IT3(a) certificates generated, you must amend the prepopulated figures to the correct amounts.
- Actual payments made in the period, excluding penalties and interest.
- Accurate payroll and employee information, including employees' tax reference numbers and the IRP5/IT3(a) certificates for 1 March to 31 August 2026.
The interim is a mid-year check. The annual reconciliation for the full tax year normally runs from 1 April to 31 May (SARS tax calendar). SARS confirms the season dates each year, so check the current notice before you plan around them. Clean up now and May is a formality. Leave it, and May is where it all comes due.
Key dates and channels for 2026
| Item | 2026 interim |
|---|---|
| Period covered | 1 March 2026 to 31 August 2026 |
| Submissions open | 21 September 2026 |
| Submissions close | 31 October 2026 (a Saturday) |
| Practical target | Friday 30 October 2026 |
Which channel to use
- e@syFile Employer works for any employer, whatever the number of certificates. SARS said it planned to release an updated build for the interim period in mid-September 2026, and that employers must download and use the latest version once released.
- SARS eFiling works too, but with a maximum of 50 IRP5/IT3(a) certificates per submission.
- Employers with five or fewer certificates who genuinely can't use either channel can book a SARS branch appointment.
If you run payroll for clients, check the BRS before you build or update payroll exports. SARS published SARS_PAYE_BRS PAYE Employer Reconciliation V25.3.0 for the 2026-08 interim period, with a new source code for ITREG to reduce duplicate income tax registrations and some minor validation changes.
Why the EMP501 bites
The penalty for a late EMP501 is not a flat fee. SARS's notice sets it at 1% of your annual PAYE, increasing by 1% for every month it stays outstanding, up to 10%.
| Label | Late EMP501 penalty as a % of annual PAYE, by months outstanding |
|---|---|
| 1 month | 1% |
| 2 months | 2% |
| 3 months | 3% |
| 4 months | 4% |
| 5 months | 5% |
| 6 months | 6% |
| 7 months | 7% |
| 8 months | 8% |
| 9 months | 9% |
| 10 months | 10% |
Source: SARS 2026 interim EMP501 notice, accessed 27 October 2026. For an employer with R600 000 annual PAYE, 1% is R6 000 and 10% is R60 000 (illustrative).
Three other consequences are easy to miss:
- Corrections cost money too. SARS attributes any shortfall you correct on the EMP501 to the last month of the reconciliation period, which can bring penalties and interest. Fixing the numbers is right. Fixing them earlier is cheaper.
- ETI can be forfeited. Employers with unused ETI lose it if they don't submit, or if their tax compliance status is non-compliant.
- It can become criminal. Wilful or negligent failure to submit an EMP201 or EMP501 is an offence that can carry a fine or up to two years' imprisonment.
The checklist
Work through this in order. Each step depends on the one before.
1. Freeze the period
- Confirm the payroll months in scope: March to August 2026.
- Stop editing closed payroll months. If something must change, do it as a documented adjustment.
2. Fix employee master data first
- Every employee needs a valid income tax number. SARS has strictly enforced this on e@syFile Employer and eFiling since the February 2026 filing season, and missing or invalid numbers can get the EMP501 rejected.
- Use ITREG or BundleReg on eFiling or e@syFile Employer, or the Tax Reference Number Enquiry Service, to register or retrieve numbers.
- Check ID numbers, names, addresses and banking details on the certificates. Small typos create big validation errors.
3. Reconcile payroll to declarations
For each month and each tax (PAYE, UIF, SDL):
- Payroll report total
- EMP201 declared amount
- Difference, with a reason
If a difference exists, decide whether the payroll or the EMP201 is wrong. Then correct the right one.
4. Reconcile declarations to payments
- Pull six months of SARS payments from the bank statements.
- Match each to its EMP201 by PRN.
- Leave penalties and interest out of the payment figure on the EMP501. SARS says payments must exclude them.
If your bank reconciliation isn't up to date, this step is painful. Our month-end bank reconciliation routine gets you there.
5. Check ETI
- Confirm every ETI claim was for a qualifying employee, at the right amount for their remuneration band.
- Any ETI you forgot to claim must be claimed in a later month within the same reconciliation period, or it's forfeited (SARS EMP201 guide). For the bands, see UIF, SDL and ETI explained.
6. Generate, review and submit
- Generate the certificates and the EMP501.
- Review the totals against your reconciliation schedule before you submit, not after.
- Submit, save the confirmation, then check the PAYE dashboard to confirm SARS processed it correctly.
7. Document what you changed
Write a short note per client: what differed, why, and what you changed. When SARS asks in six months' time, you'll have the answer in a minute.
For bureaus: run it as a production line
If you reconcile 30 or 80 employers in the same six weeks, the checklist above becomes a pipeline. A few habits help:
- Triage by risk, not by alphabet. Start with clients that have missing tax numbers, ETI claims or mid-period terminations.
- Use one reconciliation template. Same columns, same order, every client. Reviewers spot anomalies faster.
- Separate preparer and reviewer. The person who built the reconciliation shouldn't be the only one who checked it.
There's more on this in how to grow a payroll bureau without hiring more clerks.
Where IsaFlow fits
IsaFlow's payroll engine calculates PAYE, UIF and SDL from versioned SARS tax tables, and each company's books are kept separate. Accounting practices get a bureau dashboard across all their clients, set up with you during onboarding.
IsaFlow prepares VAT201 and EMP201 for you to file on eFiling, and EMP501 and IRP5/IT3(a) for you to submit through e@syFile Employer. The EMP501 exports as a CSV. For the annual reconciliation, the IRP5/IT3(a) export is also available as an e@syFile-ready import file. You review the totals and submit them through e@syFile Employer yourself.
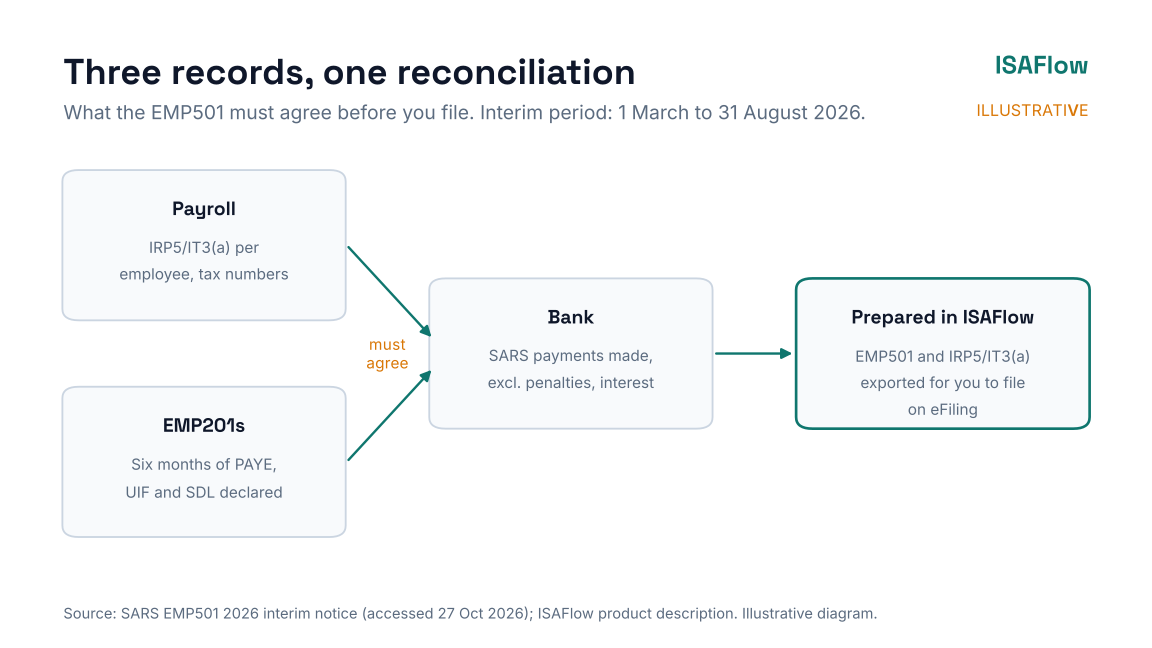
Illustrative diagram, not a screenshot.
Want to see it on your own data? Start a free trial or contact us for a demo.
FAQ
What period does the 2026 interim EMP501 cover?
1 March 2026 to 31 August 2026, the first six months of the 2026/27 reconciliation year.
When is the 2026 interim EMP501 due?
SARS's submission period runs from 21 September to 31 October 2026. Because 31 October is a Saturday, aim to be done by Friday 30 October.
Can I submit the EMP501 on eFiling?
Yes, but eFiling takes a maximum of 50 IRP5/IT3(a) certificates per submission. e@syFile Employer has no such limit.
What is the penalty for a late EMP501?
1% of your annual PAYE, increasing by 1% for every month the return stays outstanding, up to a maximum of 10%.
Should payments on the EMP501 include penalties and interest?
No. SARS says the payments on the EMP501 must exclude penalties and interest.
What happens if an employee has no income tax number?
SARS may delay processing or reject the EMP501. Register or retrieve the number through ITREG or BundleReg, or the Tax Reference Number Enquiry Service, before you submit.
Sources
All accessed 27 October 2026.
- SARS: Employer Interim Declarations (EMP501), 21 September to 31 October 2026 (published 31 August 2026)
- SARS: Completing the monthly employer declaration (EMP201)
- SARS: Tax calendar
This article is general information, not tax advice. Check your own position with a registered tax practitioner.